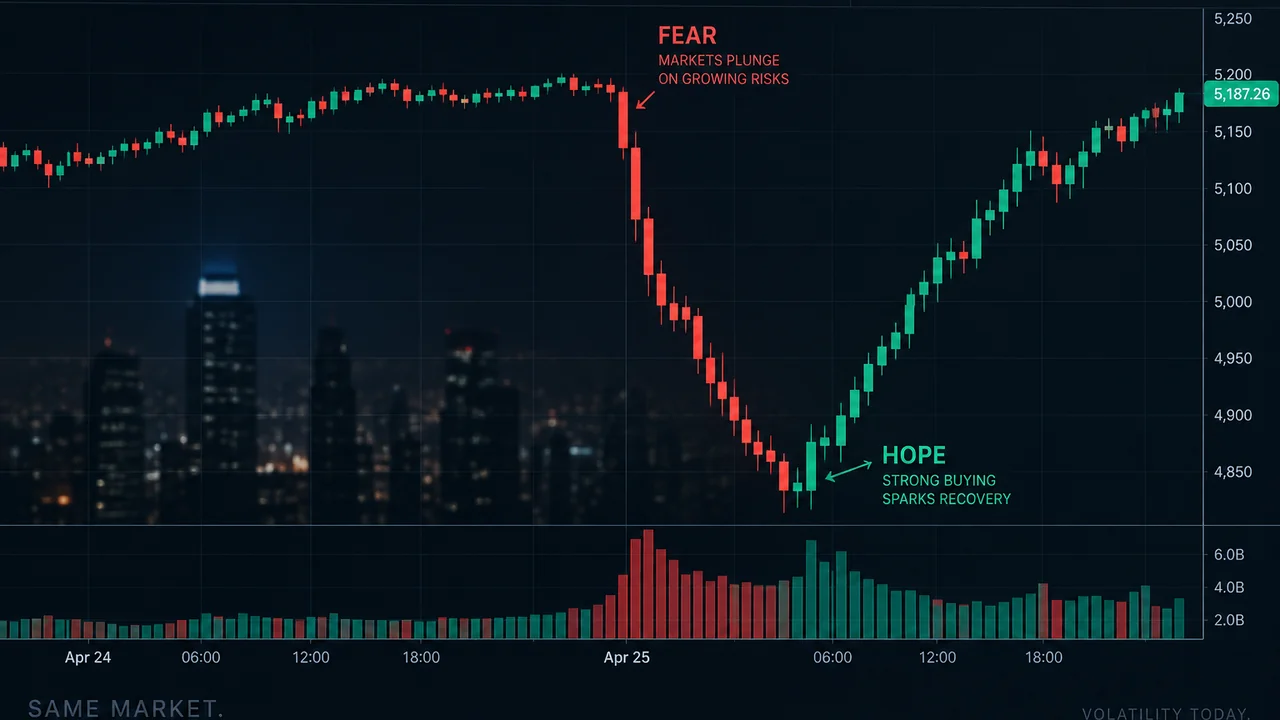
ChangXin Memory says it has reached mass production on its fifth-generation G5 DRAM process — using quadruple patterning to hit 11.95nm structure spacing without EUV tools. Samsung fell as much as 4.1% and SK Hynix about 4.0% intraday Monday in Seoul, with Micron slipping overnight in sympathy. CXMT's global DRAM revenue share climbed to roughly 10% in Q2 2026 from 4% a year earlier, and DDR5 server parts are slated by year-end.
The iShares Semiconductor ETF fell about 5% last week, its worst stretch in a month, on OpenAI revenue worries and memory competition. Monday premarket: NVIDIA up 0.1%, Intel down 1%, AMD down 0.6%, Broadcom off 0.3%, with SOXX down 1.5%. NVIDIA closed Friday at $229.28, its second straight daily decline.
Anthropic filed a confidential draft Form S-1 with the SEC on June 1, and reporting now points to a Nasdaq listing as soon as mid-November, ahead of Thanksgiving. Investors peg the valuation at $1.8 to $2 trillion — more than double the roughly $965 billion from May's Series H-1. Anthropic has not confirmed a date, price, or final valuation; treat the figures as media and analyst projections.
Taiwan Semiconductor posted Q3 revenue of roughly T$1.49 trillion, beating the T$1.46 trillion Bloomberg consensus and up about 50% year over year. September alone jumped 55% to T$511.86 billion. LSEG SmartEstimate points to net profit rising 64% to around NT$740.8 billion — a sixth straight record quarter — with the full report due October 15. Morgan Stanley keeps Overweight with an NT$3,088 target, about 21% upside.
Oracle booked more than $30 billion in new AI cloud contracts last quarter, lifting total backlog to $664 billion against roughly $24 billion in cash. Shares fell 5% Thursday on the OpenAI revenue disclosure plus a WSJ report on tech's debt-market plans, then rallied over 5% Friday as Project Jupiter in New Mexico was confirmed on track. Mizuho named Oracle its top October pick with a $320 target. Global AI-related debt issuance fell from $113 billion in June to $23 billion in September.
Broadcom is leading a planned $50 billion debt package for OpenAI's Nexus custom AI chip buildout, disclosed October 9, and has agreed to lend Anthropic up to $42 billion for chip purchases. Last quarter's print showed $29.6 billion in revenue, up 86% year over year, with AI semiconductor revenue up 221% to $16.7 billion. Broadcom presents its scale-up and scale-across AI networking stack at the OCP Global Summit in San Jose, running October 12 through 15.
Palantir closed at a record $209.05 on Friday, up 5.17%. Barclays analyst Anthony Valentini initiated at Overweight with a $265 target, and Goldman Sachs upgraded to Buy with a $230 target on October 8, arguing the addressable market may be setting up for another step-function change. Street consensus sits at $198.75 across 37 analysts — a wide spread, with the low target at $80.
A Financial Times report Thursday said OpenAI's end-September annualized revenue ran roughly $20 billion below prior indications, sending the Nasdaq down 1.25% to 27,193.34 and dragging NVIDIA and Oracle with it. The trade reversed Friday after Bloomberg sources said OpenAI still expects at least $70 billion annualized by year-end. Not a tradable name, but it's the single biggest sentiment driver in the complex right now.
Goldman lifted its NVIDIA target to $1,250 from $1,100 while holding at Neutral. Mizuho raised AMD to $705 from $580. CrowdStrike climbed premarket after Needham took its target to $310 on Falcon Flex and Next-Gen SIEM demand. Monness upgraded Elastic to Buy at $120, with Stifel matching from $107 after ElasticON checks and federal momentum.
IonQ secured up to $300 million in a DARPA deal as the quantum race accelerates, and reported entanglement rates above 1,000 per second between a trapped-ion qubit and a solid-state memory via photonic interconnect. The company also expanded commercially with a new EPB Quantum Business Program. Shares traded between $38.99 and $40.32, recently around $39.83.
 AI Stocks